Emerging Markets Join the Concentration Club
Most investors have heard the story about how concentrated the US share market has become. A handful of giant technology names, the so-called “Magnificent Seven”, now drive a huge share of returns. It has become one of the most talked-about features of developed markets, and for good reason.
What gets far less attention is that the same thing has quietly happened in emerging markets, and in some ways it is even more pronounced. The countries and companies have changed, but the underlying force is identical: the artificial intelligence boom is pulling an enormous amount of money into a very small number of stocks.
Emerging markets are no longer “a bit of everything”
It is tempting to think of emerging markets as broadly diversified, a little bit of China, India, Brazil, South Africa, the Middle East and South-East Asia all blended together. On paper that is true: the main emerging markets index holds more than 1,200 companies across two dozen countries.
Under the bonnet, though, the picture is very different. Today around four dollars in every five invested in the index goes into just four countries: Taiwan, China, South Korea and India. The shift over the past couple of years has been dramatic. Taiwan and South Korea have surged, while China and India have shrunk back.
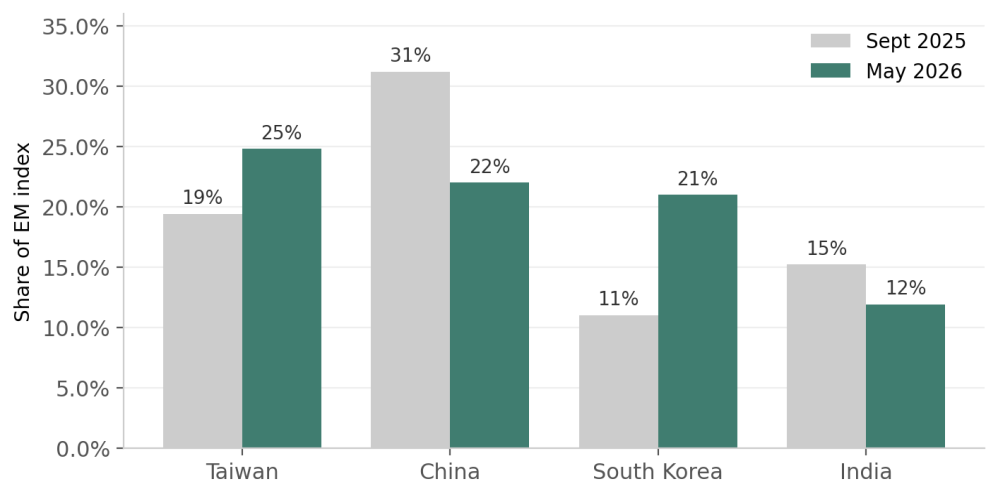
What stands out is how quickly this happened. In less than a year, Taiwan has overtaken China to become the single largest country in the index, and South Korea has roughly doubled its weight to sit alongside it. India, which many expected to keep rising, has actually slipped back to its lowest weight in more than six years, down from a peak of around 20% in 2024. The engine behind all of this is the same one driving US markets: demand for the advanced computer chips that power artificial intelligence.
Three chip stocks, almost 30% of the index
The concentration is even starker at the company level. Taiwan’s TSMC (the world’s most important chipmaker) is on its own around 14.5% of the entire emerging markets index. Add South Korea’s Samsung and SK Hynix, the two giants of computer memory, and just three companies account for close to 29% of the whole index. Stretch that to the ten largest holdings and you reach roughly a third of the index.
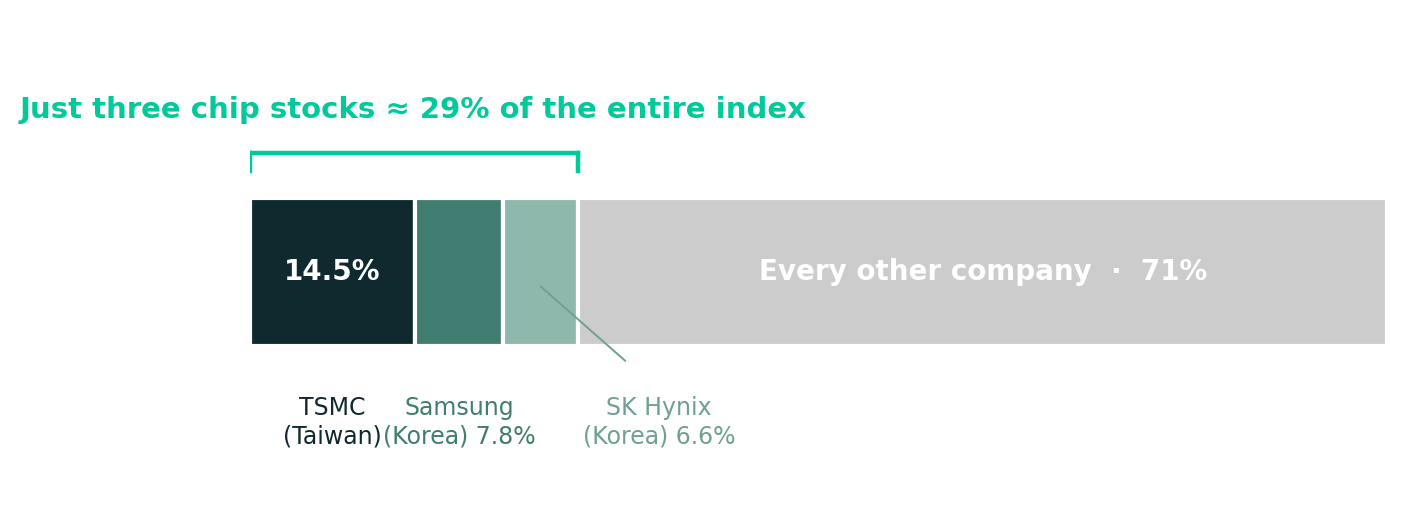
Add names such as Taiwan’s Hon Hai (the assembler behind much of the world’s electronics) and a short list of other chip and technology businesses, and a clear pattern emerges. Buying “emerging markets” today increasingly means buying the global supply chain for artificial intelligence.
Why this has caught managers off guard
This concentration has had a real effect on how professional fund managers have performed. Many active managers had owned these chip and memory companies, but typically in smaller amounts than the index, because for years they looked expensive relative to their earnings. As these same stocks have raced ahead on AI enthusiasm, being underweight them has been costly.
The chart below shows the gap. Over the past three years, the technology-heavy part of the emerging markets index has left the broader market far behind, turning $100 into around $249, versus $160 for the index as a whole.
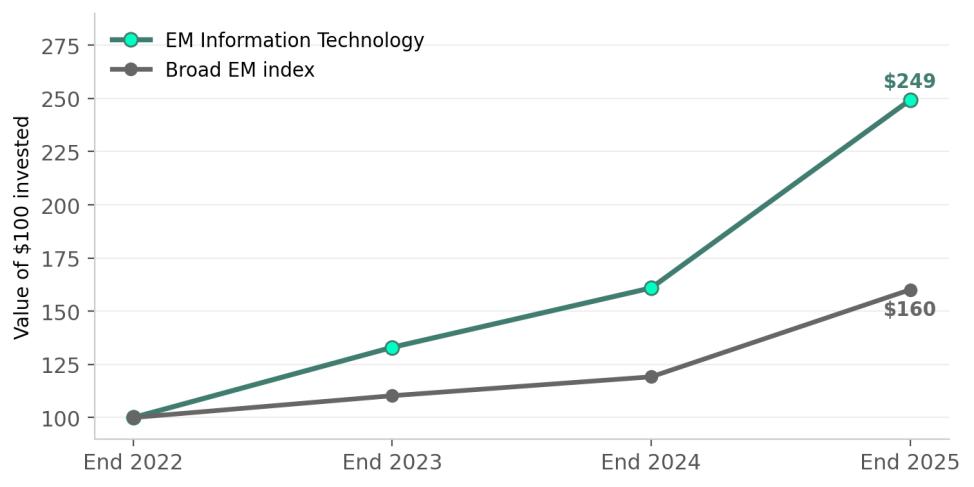
Growth of $100, end-2022 to end-2025. Source: MSCI index returns (EM Information Technology vs broad EM).
The result is that a manager could have made sensible, disciplined decisions (avoiding stocks that looked richly priced) and still ended up behind a simple index fund, purely because they didn’t hold enough of a few rampaging chip stocks. It is the emerging markets echo of a story that has frustrated active managers in the US for years.
What this means for your portfolio
None of this means these are bad companies, TSMC, Samsung and SK Hynix are among the most important businesses on the planet. But there are two things worth keeping in mind.
- You may own less diversification than you think . An emerging markets fund can look spread across dozens of countries while, in reality, leaning heavily on a few chip stocks in Taiwan and Korea. Much of its fate now rests on a single theme: artificial intelligence.
- Today’s strong run reflects enthusiasm as much as earnings. A lot of the recent gains are built on optimism about where AI demand is heading, rather than profits already in the bank. That can continue for a long time, but it also makes these stocks, and the index that leans on them, more sensitive to any disappointment.
Our approach has not changed. We continue to favour genuine diversification (across countries, sectors and styles) rather than letting a portfolio quietly become a concentrated bet on one theme. Periods like this are a useful reminder that what looks like broad exposure can sometimes be anything but.
Latest insights
You might also like