The Case for Active Management: The Struggle is Real, But the Story Isn’t Over
It's been a hard few years to be an active manager, and the data backs that up. Across most major markets, a majority of active equity funds have underperformed their benchmarks. It's a fair question for investors to ask: why bother? The answer requires looking past the headline numbers to what's actually driving them.
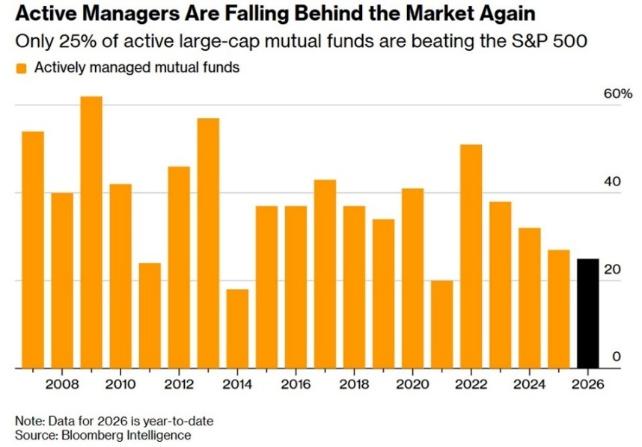
Why active has struggled – the structural story
The honest explanation is structural, not purely about manager skill. A few forces have combined:
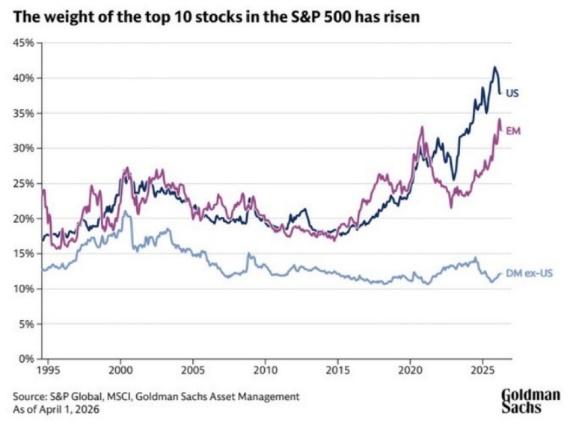
Extreme concentration in equity indices. This kind of concentration (see below) is anathema to diversified active strategies, most of which are prohibited – by design and by client mandate – from holding the 20–30% position sizes in a handful of mega-company names that a capitalisation-weighted index effectively does. When a small number of stocks drive most of the index return, a manager has to be right about exactly those names, in roughly that weighting, just to match the benchmark.
The consistent thread: wherever a handful of mega-cap stocks dominated index returns, active managers with diversified, risk-managed portfolios struggled to keep pace. Wherever markets were less concentrated, or where inefficiencies were greater – small companies, emerging markets (until recently), and bonds – active managers held up far better, and in many cases outperformed.
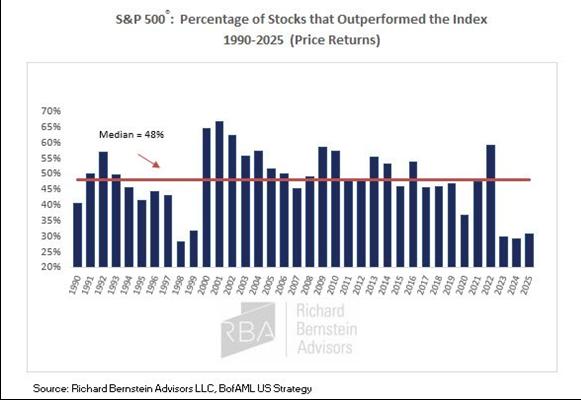
Narrow market breadth. Breadth, that is how many stocks are participating in a rally (see below), has been unusually thin, particularly in large company focused mandates. Thin breadth compresses the opportunity set for genuine stock-picking to add value. You can also see in the below that breadth widens significantly after market turmoil, e.g. 1999-2000.
A volatile rate and macro backdrop. Shifting inflation and rate expectations, given unconventional central bank policy, largesse government spending, and heightened geopolitical risks have repeatedly wrong-footed active positioning across equities and, at times, fixed income, particularly where managers had taken on the correct positioning that didn't pay off in the expected timeline.
This has not been uniform across asset classes. The struggle had been concentrated specifically in large-cap Australian and global equity mandates, precisely where index concentration has been most extreme.
But has since spread to other asset classes and sub-asset classes including small companies, emerging markets, and listed property. In contrast, active management has held up better in bonds.
What investors should consider
Concentration this extreme is historically unusual, not the norm. Index leadership this narrow tends not to persist indefinitely. When market breadth widens – as it typically does over a cycle – the conditions that punished diversified stockpickers usually ease, and the dispersion between winners and losers that active management depends on tends to widen with it.
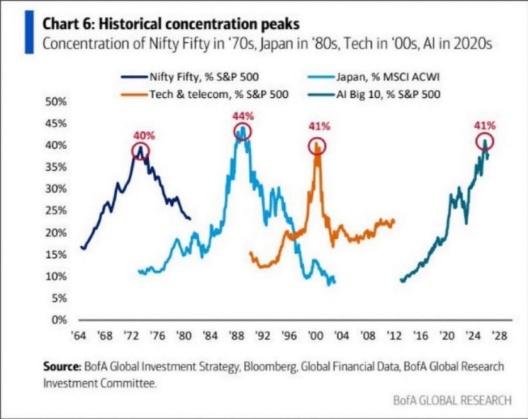
Investment Committee.
"Active vs passive" is too blunt a framing. The data makes clear that asset class, region, and market segment matter enormously. Blanket statements obscure real and persistent differences: bonds, small companies, and less efficient markets have offered better hunting ground for skill over the longer-term than concentrated large company equity indices. A well-constructed multi-asset portfolio can and should use both tools depending on where each is best suited.
Averages hide dispersion between managers. Industry measures of active outperformance are conducted at the category, not any individual manager. A rigorous, well-governed manager research and selection process – with clear criteria for buy, retain, sell and remove decisions, and genuine ongoing monitoring – is critical to identify the funds more likely to justify their fees in producing long-term risk-adjusted outperformance, rather than simply accepting the category average.
The promises of passive investing. Passive investing was sold on three promises: it’s cheap, it’s diverse and it’s liquid. Only the first promise really holds today. Passive is cheap. Liquidity somewhat still holds, but in some markets like Australia there’s been observed drop in liquidity even in large company names. The diversity benefits of passive have been diluted thanks to an increasing concentration in a small group of mega companies and sectors. So much so, that active strategies are now arguably more diversified than passive.
Risk management and customisation are active strengths. Passive strategies deliver market exposure (beta). That’s valuable. But they also deliver market drawdowns, in full force. In an era of heightened geopolitical risk, inflation volatility, interest rate uncertainty, technological disruption, and demographic shifts, many investors need more than beta. They need active risk management: downside protection, sector rotation, dynamic allocation, and customized solutions that align with specific preferences, approaches, liabilities, or tax situations.
The cycle may be turning. After years of passive dominance, conditions are shifting. Higher interest rates will restore the value of fundamental investing. Dispersion within sectors is increasing as the AI boom creates clear winners and losers. Regulatory changes, deglobalisation, and energy transitions are creating structural inefficiencies that patient, research-driven investors can exploit. History shows that active management tends to shine after periods of concentration and complacency.
The bottom line
The case for active management was never that it always wins, it's that in the right segments, backed by rigorous manager selection and judged over a full cycle rather than a difficult stretch, it can still earn its place in a well-constructed portfolio. Active investment management has struggled because markets are competitive and many strategies failed to deliver on their promise. But it is not dead, because human ingenuity, specialised knowledge, and adaptive risk management remain essential in a complex, everchanging world.
Latest insights
You might also like